
Investment and savings fintechs in France
Investment and savings fintechs in France
 29 September 2026
Abstract
A map of the French online savings and investment market: twenty players benchmarked on six axes (product, pricing, customer reviews, size, funding, go-to-market), market dynamics, whitespace and implications by type of player. Covers January 2025 to September 2026, built from 44 public sources.
Key findings
- 01
The contest is for new money, and foreign providers are winning it: 61% of new equity investors used a provider established outside France (2025).
- 02
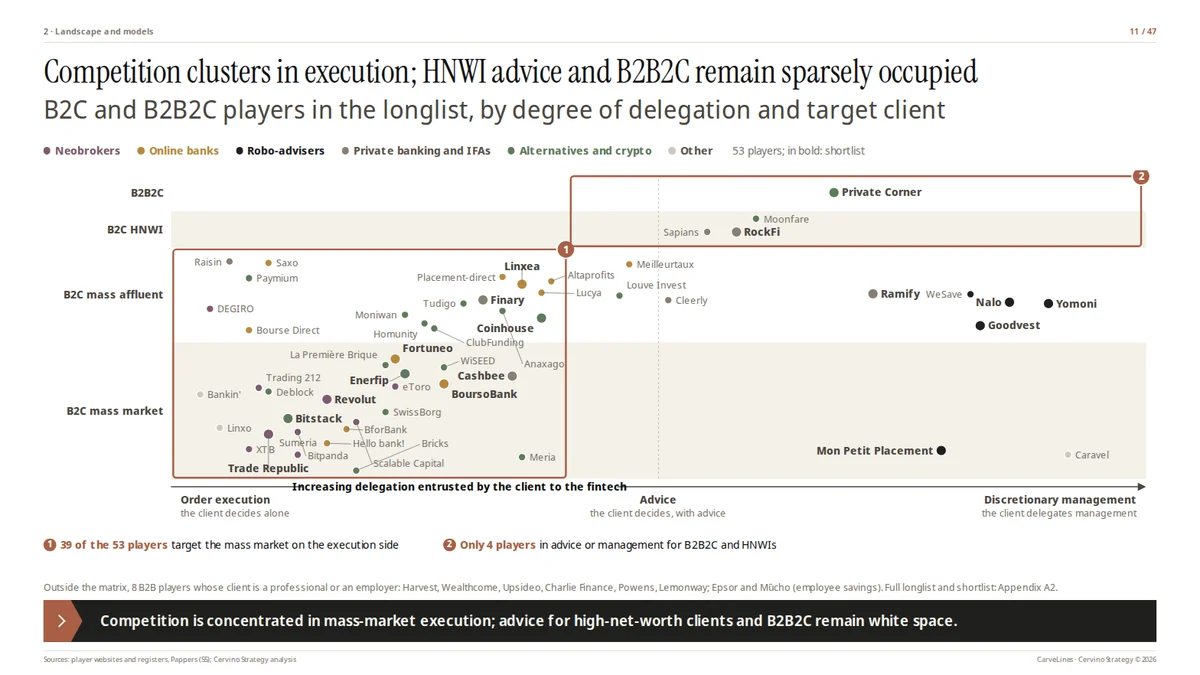
Everyone targets the mass market, and each model is extending into the next box: 49 of the 61 players on the longlist target mass market or mass affluent clients.
- 03
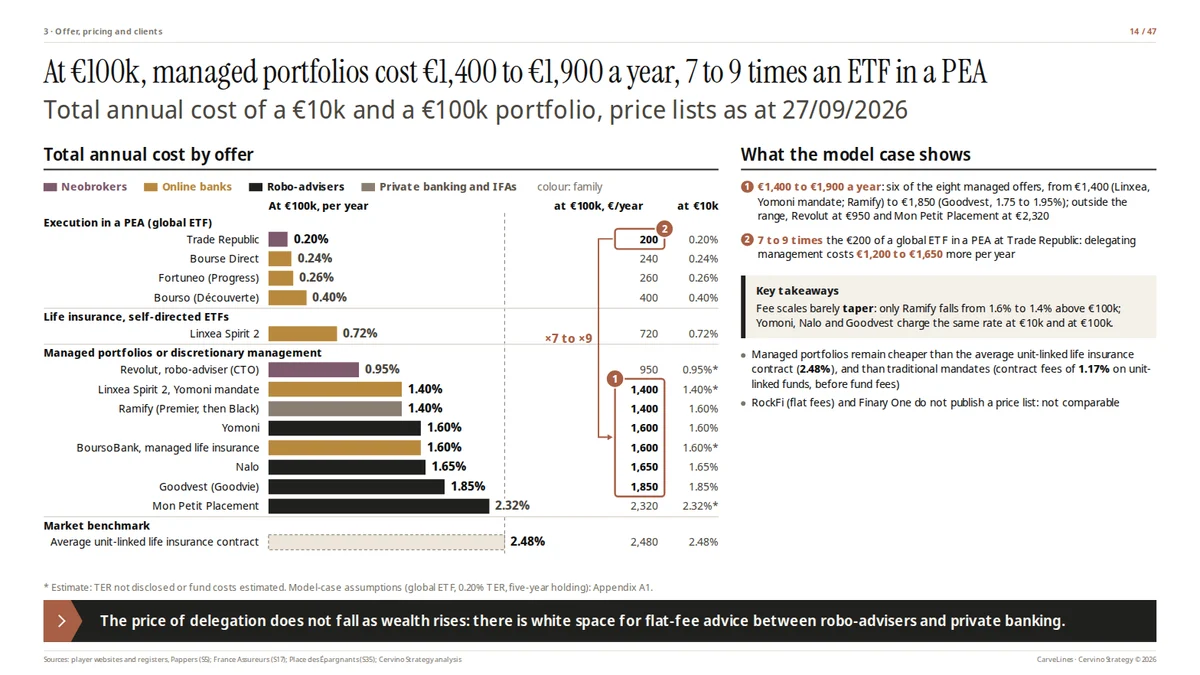
Execution is a loss leader; managed portfolios remain expensive and barely degressive: at €100k, they cost 7 to 9 times an ETF held in a PEA.
- 04
Profitability comes from scale, from being the product issuer or from B2B: about €2bn of assets is the break-even point observed at the leading robo-advisor.
- 05
Insurers, mutual groups and funds are buying digital distribution and infrastructure: 42 fintech M&A deals in France in 2025.
- 06
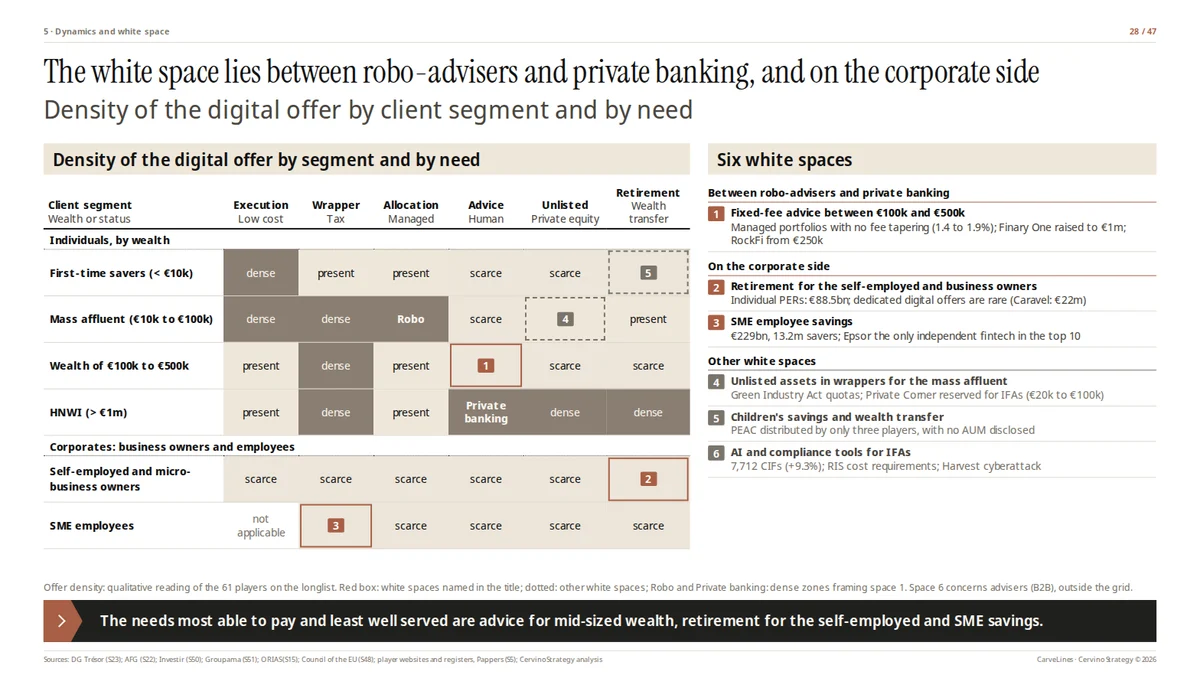
The least-served needs sit between robo-advisers and private banking, and on the corporate side: fixed-fee advice for €100k to €500k portfolios, retirement for the self-employed, SME employee savings.
Selected pages
Methodology and sources
88 players identified, 61 kept on the longlist and 20 on the shortlist, at least one per segment. Classified on three axes (segment, regulatory status, target client) and compared on six. Data collected on 27/09/2026 from company websites and legal notices, the AMF, ORIAS and REGAFI registers, Pappers, specialist press, Trustpilot and app stores. Any figure a player does not publish is flagged as an estimate with its method; eighteen structural facts were re-checked against primary sources.
Related use cases
Need a study like this on your market?
Send us the market question and the decision it serves.